Understanding the difference between company cars and pool cars for tax purposes
Written by the Brickbooks and Payroll team. Reviewed by a MAAT-qualified accountant. First published 10 September 2024. Last reviewed: 19 October 2026 (rates checked on gov.uk on 18 October 2026).
If your business provides vehicles for staff, how they’re used decides the tax. This guide explains the difference between company cars and pool cars, and covers vans and double cab pick-ups too, because that’s what many trades and construction businesses run. The HMRC sources are listed at the end.
Company cars and pool cars: the short answer
- Company car: a car you provide that an employee can use for private journeys, including commuting. The employee pays tax on it as a benefit in kind, and you pay Class 1A National Insurance on it.
- Pool car: a car shared by employees for business only, that passes all 5 of HMRC’s tests. There’s no tax, no Class 1A and nothing to report (HMRC guidance).
- Vans have their own rules. A van used only for work and commuting, with no more than insignificant other private use, has no van benefit charge.
- From April 2027, tax on company cars and vans moves into payroll.
What is a company car?
A company car is one you provide to an employee that’s available for private use. That includes driving to and from their normal workplace. HMRC treats this as a benefit in kind.
Tax on a company car
- For the employee: the taxable value is the car’s list price (plus some accessories) multiplied by a percentage set by its CO2 emissions. Low and zero emission cars have lower percentages. For cars at 75g/km and above, the percentage is capped at 37% (HMRC guidance).
- Fuel: if you pay for fuel for private journeys, there’s a separate car fuel benefit. For 2026 to 2027 it’s worked out from a figure of £29,200, multiplied by the same CO2 percentage (HMRC guidance).
- For the employer: Class 1A National Insurance on the value of the benefit. The rate for 2026 to 2027 is 15% (HMRC guidance).
HMRC’s company car tax calculator works out the figures for a specific car.
What is a pool car?
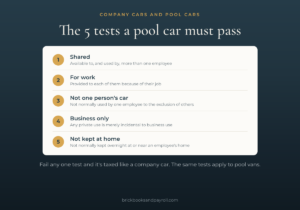
A pool car is a car that’s shared for business. To count as a pool car, it must pass all 5 of these tests (HMRC 480, chapter 15):
- Shared. It’s available to, and actually used by, more than one employee.
- For work. It’s provided to each of them because of their job.
- Not one person’s car. It isn’t normally used by one employee to the exclusion of the others.
- Business only. Any private use is merely incidental to business use, for example a short stop on the way back from a job.
- Not kept at home. It isn’t normally kept overnight at or near an employee’s home, unless it’s kept on the employer’s premises.
HMRC treats a car as not normally kept at home overnight if it’s taken home on no more than 60% of occasions in the year. A car that’s taken home because there isn’t enough parking at work fails test 5 (HMRC 480, chapter 15).
If a car fails any one test, it isn’t a pool car, and it’s taxed like a company car. That’s the key tax difference between company cars and pool cars.
Company cars and pool cars side by side
- Who uses it: company car, usually one employee. Pool car, shared by more than one.
- Private use: company car, allowed. Pool car, only incidental to business use.
- Kept at home overnight: company car, yes. Pool car, normally no.
- Employee tax: company car, benefit in kind. Pool car, none.
- Employer Class 1A NI: company car, 15% of the benefit. Pool car, none.
- Reporting: company car, reported to HMRC. Pool car, not reported.
These are the main tax differences between company cars and pool cars.
Vans: the rules most trades need
Company vans
Vans follow similar ideas to company cars and pool cars, with their own charges. A van is taxed differently from a car. If the van is only available for business travel and commuting, and any other private use is insignificant, there’s no van benefit charge (HMRC 480, chapter 14).
- Insignificant: a short detour to buy a newspaper on the way to work. A weekly supermarket shop or a week’s holiday is not insignificant (HMRC guidance).
- If there is more private use: the flat van benefit charge for 2026 to 2027 is £4,170, plus £798 van fuel benefit if you pay for private fuel (HMRC guidance).
- Zero emission vans: the van benefit charge is nil (HMRC 480, chapter 14).
Pool vans
Vans can be pool vans too. They need to pass the same 5 tests as pool cars (HMRC 480, chapter 15).
Double cab pick-ups
From 6 April 2025, most double cab pick-ups are treated as cars, not vans, for benefit in kind. If you bought, leased or ordered one before 6 April 2025, the old van treatment can continue until you sell it, the lease ends, or 5 April 2029, whichever comes first (HMRC manual EIM23151).
VAT on cars
- Buying a car: VAT can’t usually be reclaimed. The exception is a car used only for business, with no private use. Pool cars kept at your main place of business and not allocated to one person can qualify (VAT Notice 700/64).
- Repairs and maintenance: you can reclaim the VAT if the vehicle is used for business and the business pays, even if it’s also used privately (VAT Notice 700/64).
- Fuel: if you reclaim VAT on fuel and there’s private use, a fuel scale charge may apply (VAT Notice 700/64).
For more on VAT in trades and construction, see VAT tips for construction businesses.
What’s changing from April 2027
The way company cars and pool cars are reported is changing.
From 6 April 2027, company cars, car fuel, vans and van fuel must be reported and taxed through payroll in real time, instead of through a P11D after the end of the year (HMRC employer bulletin, August 2026). Most other benefits follow from April 2028. For the current rules, see P11Ds and benefits in kind.
For keeping payroll on track, see payroll compliance explained and payroll for construction businesses.
Questions people ask:
Common questions about company cars and pool cars:
What’s the difference between company cars and pool cars?
A company car is available to an employee for private use and is taxed as a benefit in kind. A pool car is shared, used for business only, normally kept at work, and isn’t taxed (HMRC guidance).
Can an employee take a pool car home?
Only occasionally. A pool car can’t normally be kept overnight at or near an employee’s home. HMRC uses a 60% guide: taken home on more than 60% of occasions and it fails the test (HMRC 480).
Is driving a company van to and from work a taxable benefit?
Not on its own. A van available for business travel and commuting, with only insignificant other private use, has no van benefit charge (HMRC 480, chapter 14).
Do I need to report a pool car to HMRC?
No. Pool cars that pass all 5 tests don’t need to be reported, and there’s nothing to pay (HMRC guidance).
Is a double cab pick-up a car or a van?
For benefit in kind, most double cab pick-ups bought from 6 April 2025 are cars (HMRC manual EIM23151).
Records to keep
Keep records for company cars and pool cars alike. For a pool car or pool van, keep a log of who used it, when, and for which business journeys, and where it was kept overnight. That’s what shows it passed the 5 tests. For a company car or van, keep the list price, CO2 figure and dates it was available. For capital allowances on vehicles, see are tools an expense or an asset.
For which running costs count, see tax deductible expenses, and for what to keep at year end, see records to keep for year end accounts.
Company cars and pool cars: a quick checklist
Run through these to sort your company cars and pool cars:
- Is it shared by more than one employee, for business only?
- Is it normally kept at work overnight, not at someone’s home?
- If it’s a van, is private use limited to commuting and insignificant trips?
- Is it a double cab pick-up bought from 6 April 2025? Then it’s probably a car for benefit in kind.
- Is your payroll software ready to report car and van benefits from April 2027?
This is general information, not advice on your own position. How the rules apply depends on your circumstances, so check the HMRC guidance linked here or take advice on your own situation before acting.
Brickbooks and Payroll Ltd, company number 14528647, licensed and regulated by the AAT, registered Authorised Corporate Service Provider (ACSP) with Companies House.
Sources
- Company cars, what’s exempt
- Company vans, what’s exempt
- HMRC 480 chapter 15: pooled cars and vans
- HMRC 480 chapter 14: company vans available for private use
- Appropriate percentages for company cars 2025 to 2028
- Van and fuel benefit charges 2026 to 2027
- Rates and thresholds for employers 2026 to 2027
- HMRC manual EIM23151: double cab pick-ups
- HMRC: VAT on motoring expenses (Notice 700/64)
- HMRC: Employer bulletin, August 2026
- Calculate tax on employees’ company cars